-
Shop
- Advanced Technologies
- AI Career Advantage Collection
- AI Skills
- AI Skills for Creators & Freelancers
- AI Client Management
- AI Ethics
- AI Mindset
- AI Tools & Prompts
- AI Writing & Content Creation
- Audio, Voice & Music
- Design & Visual Creation
- Email, Messaging & Communication
- Freelancing & Business
- Marketing, Ads & Conversion
- Productivity, Workflow & Automation
- SEO & Search Optimization
- Social Media Content & Growth
- Strategy, Planning & Analytics
- Video Creation & Editing
- Bathroom
- Beauty
- Best-Sellers
- Car Accessories
- Car Buying & Ownership
- Confidence
- Dating & Social Skills
- Digital Resources
- AI & Technology
- Budgeting & Saving
- Cozy Feast Collection
- Electronics & Technology
- Emotional Intelligence
- Entrepreneurship & Business Growth
- Financial Education
- Financial Independence
- Financial Mindset & Psychology
- Goal Setting
- Hobbies
- Kitchen & Recipes
- Leadership
- Mindfulness
- Mindset
- Motivation
- Online Business
- Positive Thinking
- Productivity
- Self Confidence
- Sleep Improvement
- Smart Life with AI
- Stress Management & Relaxation
- Travel Planning
- Yoga & Fitness
- Yoga & Mind-Body Practices
- Education & Learning
- Family & Parenting
- Gadgets
- Health & Beauty
- Health & Wellness
- Home & Garden
- Home Styling & Organization
- Home Supplies
- Kids & Babies
- Legend Footwear Brands Collection
- Online Business for Beginners
- Parenting & Child Development
- Patio, Lawn & Garden
- Personal Growth
- Personal Style & Fashion
- Pet Care
- Pet Lifestyle & Wellness
- Pet Supplies
- Pets
- Smart Amazon Shopping
- Stress Relief & Relaxation
- TikTok Growth & Monetization Mastery
- Travel
- Travel & Adventure
- Wealth
- Wellness
- Popular
- Best deals
Where to Keep Down Payment Savings Before Closing
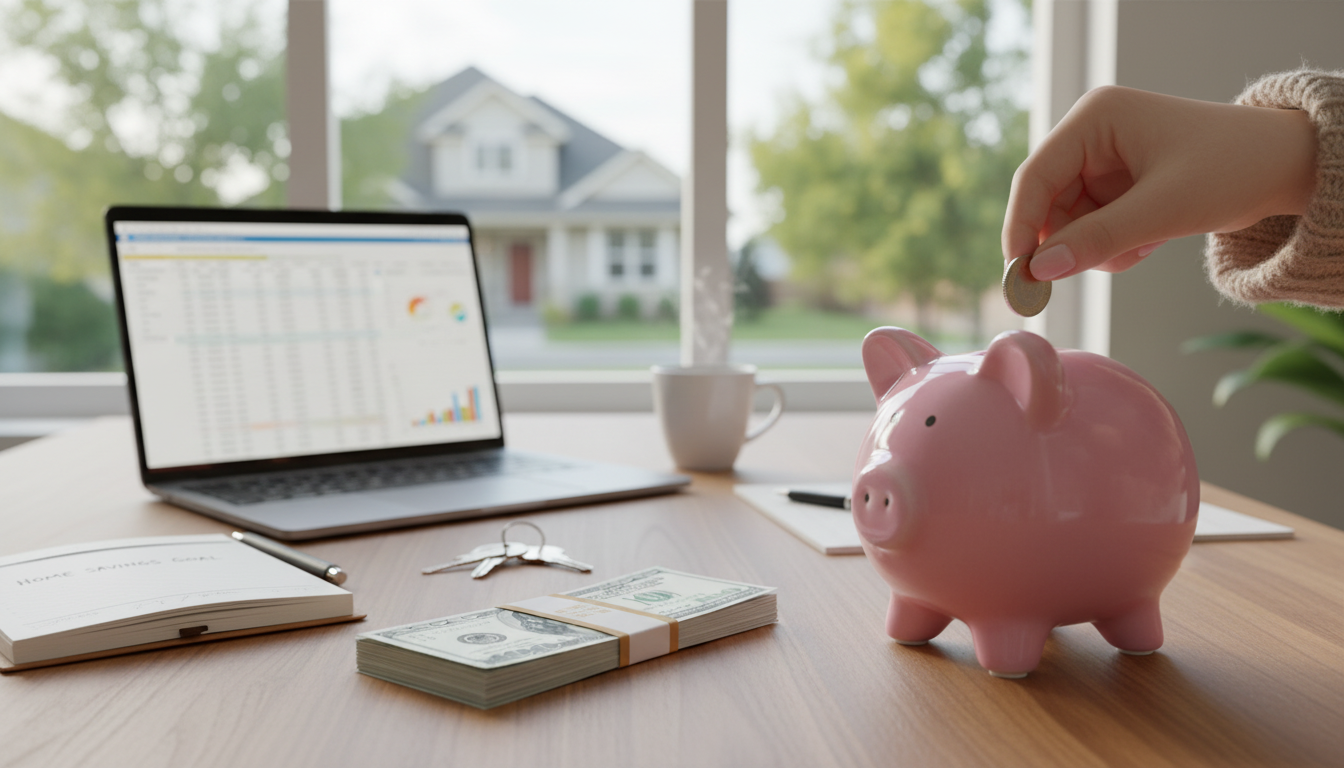
Where should you keep your down payment?
Choose a place that protects your savings and lets you access the money when you need it. For most buyers, that means an FDIC-insured bank account or an NCUA-insured credit union account—not an investment that could lose value just before closing.
Is a high-yield savings account a good choice?
A high-yield savings account can be a practical home for down payment funds. It typically keeps your money accessible while earning interest, and eligible deposits are insured up to applicable limits. Confirm the institution’s insurance status, account terms, withdrawal rules, and any fees before moving your savings.
Could a money market account or CD work?
A money market deposit account may offer a competitive rate and convenient access, but review its minimum balance and transaction terms. Don’t confuse it with a money market mutual fund, which is an investment and is not FDIC-insured.
A certificate of deposit can suit money you won’t need immediately. Match its maturity date to your expected purchase timeline, and understand early-withdrawal penalties. If your closing date could change, avoid locking up funds you may need on short notice.
Should you invest your down payment?
Usually, money needed for a near-term home purchase belongs in a stable, liquid account rather than stocks, cryptocurrency, or long-term bonds. A market drop or withdrawal delay could leave you short when you need to pay closing costs. Keep this goal separate from investments meant for longer-term growth.
What should you consider before closing?
Keep a clear record of where the money came from and avoid unnecessary transfers between accounts. Mortgage lenders may ask you to document deposits and verify available funds, so save statements and transfer confirmations. Ask your lender when the down payment must be accessible and whether your chosen account could complicate verification.
Also set aside money for moving, immediate home expenses, and an emergency cushion instead of committing every dollar to the purchase. For a step-by-step account comparison, visit our down payment savings checklist.
FAQ
How much cash should I keep available after closing?
Set aside money for moving, immediate home expenses, and an emergency cushion before using all your savings for the purchase. The right amount depends on your monthly costs, job stability, and the condition of the home.
Recommended for you
3 Essential Skills Every Virtual Assistant Needs
Sep 30, 2026



Leave a comment