-
Shop
- Advanced Technologies
- AI Career Advantage Collection
- AI Skills
- AI Skills for Creators & Freelancers
- AI Client Management
- AI Ethics
- AI Mindset
- AI Tools & Prompts
- AI Writing & Content Creation
- Audio, Voice & Music
- Design & Visual Creation
- Email, Messaging & Communication
- Freelancing & Business
- Marketing, Ads & Conversion
- Productivity, Workflow & Automation
- SEO & Search Optimization
- Social Media Content & Growth
- Strategy, Planning & Analytics
- Video Creation & Editing
- Bathroom
- Beauty
- Best-Sellers
- Car Accessories
- Car Buying & Ownership
- Confidence
- Dating & Social Skills
- Digital Resources
- AI & Technology
- Budgeting & Saving
- Cozy Feast Collection
- Electronics & Technology
- Emotional Intelligence
- Entrepreneurship & Business Growth
- Financial Education
- Financial Independence
- Financial Mindset & Psychology
- Goal Setting
- Hobbies
- Kitchen & Recipes
- Leadership
- Mindfulness
- Mindset
- Motivation
- Online Business
- Positive Thinking
- Productivity
- Self Confidence
- Sleep Improvement
- Smart Life with AI
- Stress Management & Relaxation
- Travel Planning
- Yoga & Fitness
- Yoga & Mind-Body Practices
- Education & Learning
- Family & Parenting
- Gadgets
- Health & Beauty
- Health & Wellness
- Home & Garden
- Home Styling & Organization
- Home Supplies
- Kids & Babies
- Legend Footwear Brands Collection
- Online Business for Beginners
- Parenting & Child Development
- Patio, Lawn & Garden
- Personal Growth
- Personal Style & Fashion
- Pet Care
- Pet Lifestyle & Wellness
- Pet Supplies
- Pets
- Smart Amazon Shopping
- Stress Relief & Relaxation
- TikTok Growth & Monetization Mastery
- Travel
- Travel & Adventure
- Wealth
- Wellness
- Popular
- Best deals
Rewards Cards for Beginners: A Simple Checklist
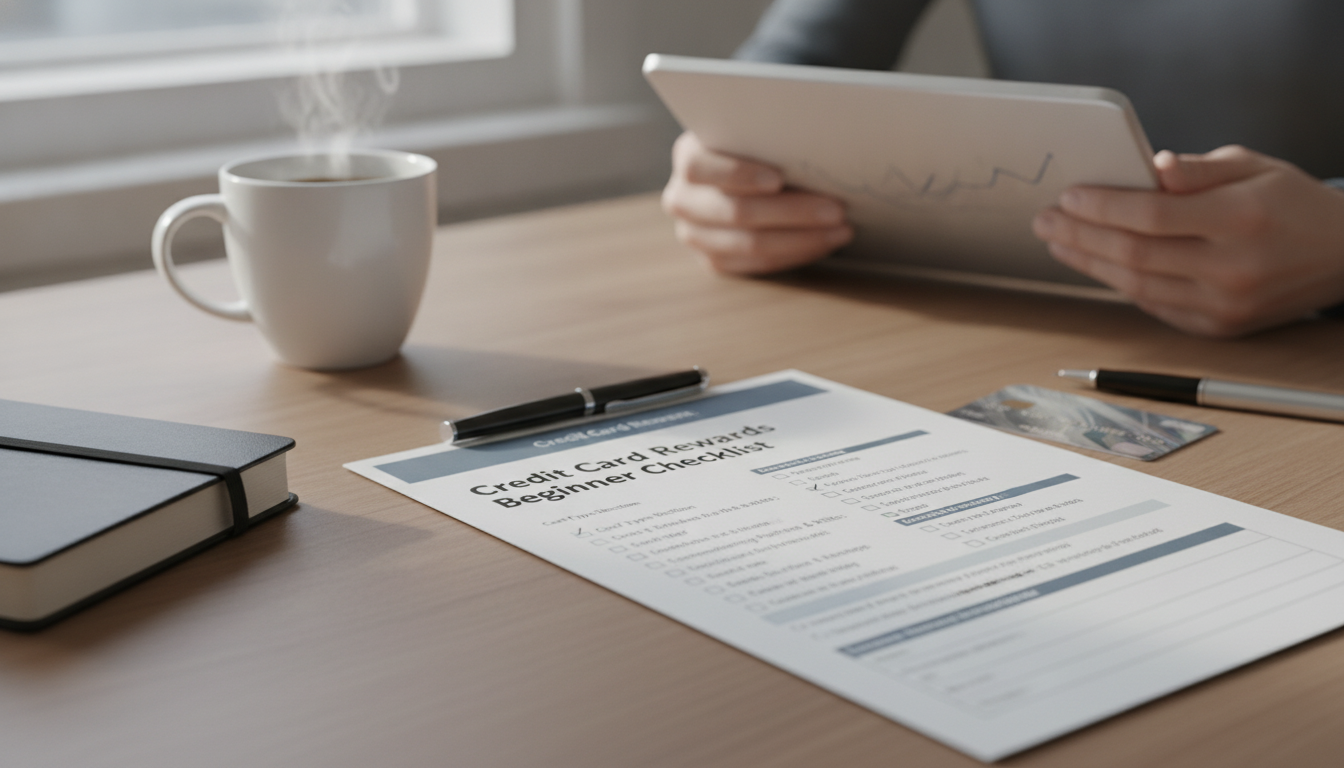
Credit Card Rewards Beginner Checklist – Maximize Your Benefits and Boost Financial Health
Credit card rewards can be a powerful tool when paired with a simple system: choose the right card, activate the right perks, spend intentionally, redeem strategically, and protect credit health. This beginner-friendly checklist breaks the process into clear steps so rewards grow without adding fees, interest, or stress.
Start With the Right Mindset: Rewards Are a Bonus, Not a Reason to Spend
The fastest way to “lose” at rewards is to let points convince you to buy more than you planned. A clean baseline mindset keeps everything else easy.
- Treat every purchase as cash: if it cannot be paid in full by the due date, skip the charge.
- Set a single goal for the next 90 days (cash back, a specific trip, statement credits, or gift cards) to keep choices simple.
- Know the three biggest reward-killers: carrying a balance, missing payments, and paying fees that outweigh benefits.
- Decide on a “one-card” or “two-card” setup: one general-purpose card, plus one category booster only if spending is consistent.
Choose a Rewards Style That Matches Real Spending
Rewards are only “good” if they fit what you already buy. Start with the structure that requires the least effort for the most predictable value.
- Cash back: simplest value; ideal for beginners and for flexible budgeting.
- Points/miles: best when redemptions are planned; value varies by program and how points are used.
- Flat-rate vs category rewards: flat-rate reduces effort; category rewards can outperform if categories match spending (groceries, gas, dining, travel).
- Check for caps and exclusions: quarterly limits, category activation requirements, and merchants that code differently than expected.
| Reward type | Best for | Watch out for | Beginner tip |
|---|---|---|---|
| Flat-rate cash back | Simple everyday spending | Lower upside than category cards | Use as the default card for non-bonus purchases |
| Category cash back | Consistent spending in 1–3 categories | Caps, activation, merchant coding | Pick categories already in the budget (not aspirational) |
| Travel points/miles | Planned travel and flexible dates | Variable redemption value, blackout rules, transfer complexity | Start with statement credits or travel portal bookings before transfers |
| Store/brand rewards | Frequent purchases with one merchant | Limited redemption options, higher APR risk | Use only if savings clearly exceed any fees |
Set Up the Card for Success in the First 30 Minutes
A few settings prevent nearly every beginner mistake: missed payments, interest surprises, and unnoticed fraud.
- Enable autopay for at least the minimum payment immediately; then switch to autopay “statement balance” if cash flow supports it.
- Set payment reminders 7–10 days before the due date to avoid missed payments and interest.
- Turn on purchase alerts and set a spending notification threshold to catch fraud and overspending early.
- Download the issuer app and locate: rewards dashboard, benefits tab, customer service number, and dispute flow.
- Confirm key dates: statement closing date (impacts utilization reporting) and payment due date (avoid late fees).
For additional card basics and consumer protections, use the Consumer Financial Protection Bureau’s credit card resources.
Earn More Without Spending More: A Beginner Checklist
Higher rewards come from better routing and consistency—not bigger shopping carts.
Redeem Strategically: Turn Rewards Into Real Value
| Goal | Good redemption choice | Why it works |
|---|---|---|
| Lower monthly expenses | Statement credit or direct deposit | Immediate, predictable value |
| Build an emergency cushion | Direct deposit to savings | Rewards become buffer without new spending |
| Plan a trip | Travel portal booking | Easy comparison shopping and clear pricing |
| Maximize travel value (advanced) | Transfer to partners | Potentially higher value, but requires rules knowledge |
Protect Financial Health: Interest, Fees, and Credit Score Basics
To understand what typically drives a credit score (and what doesn’t), review myFICO’s credit education, plus general credit and debt guidance from the Federal Trade Commission.
Build a Maintenance Routine (Monthly and Quarterly)
| Timing | Task | Result |
|---|---|---|
| Weekly (optional) | Track bonus progress and big category spending | Prevents missed bonuses and overspending |
| Monthly | Pay in full, audit transactions, confirm rewards posted | Avoids interest and catches issues early |
| Quarterly | Activate categories, redeem/verify balances | Keeps rewards from stagnating or expiring |
| Annually | Review fees, benefits used, and goal fit | Optimizes long-term value and simplicity |
Helpful Resources (Digital Downloads)
- Credit Card Rewards Beginner Checklist – Maximize Your Benefits and Boost Financial Health ($5.99)
- Clear Pathways: Mastering High-Traffic Spaces at Home | How to Keep High Traffic Areas Clear | Home Organization Guide for Clutter-Free Living ($6.99)
- Speak Up, Shine Bright: Unlocking Confident Communication – A Practical Guide on how to build confidence in communication skills for Work, Life & Leadership ($10.99)
FAQ
Is it worth using a rewards card if a balance might be carried?
Usually not, because interest charges typically outweigh the value of rewards. Focus on paying in full; if you need time, a 0% intro APR can help when used with a payoff plan and no new revolving debt.
Does redeeming points or cash back affect credit score?
No—redemption itself doesn’t change your credit score. Your score is mainly influenced by payment history, utilization, and new credit activity; a statement credit can reduce what you owe but doesn’t change your credit limit.
How many rewards cards should a beginner have?
Start with one strong “default” card you can pay in full every month. Add a second card only if a specific category bonus matches consistent spending and managing due dates remains effortless.





Leave a comment